Anthropic IPO Filing Reveals RSI Risks and Massive Financials
Anthropic's updated IPO filing formally acknowledges that its next-generation models may breach the 'Recursive Self-Improvement' (RSI) safety threshold. The document also reveals a 1127% YoY revenue surge to $17B in Q3, alongside widening net losses and a staggering $895.4B compute procurement bill, raising concerns about uncontrolled AI acceleration and commercial sustainability.
Full Report
Contents2 sections
Anthropic Raked in 113 Billion RMB in a Single Quarter, But…
By Yu Yang, from Ao Fei Si QbitAI | WeChat Official Account: QbitAI
Anthropic is on the verge of losing control over RSI.
Just moments ago, Anthropic updated its prospectus, officially disclosing financial data for the third quarter of this year.
But let's save the money talk for later. The most hair-raising sentence was quietly tucked away by Anthropic on page 29 of the prospectus:
Their next-generation model is about to cross the dangerous red line of RSI (Recursive Self-Improvement).
"We are increasingly using AI to accelerate AI research and development, which may lead to improvements in model capabilities outpacing our ability to develop, validate, and implement corresponding safety, alignment, and security measures." "Our internal assessments suggest that our models may soon reach the threshold defined in our Responsible Scaling Policy (RSP) as 'significant acceleration driven by AI.'"
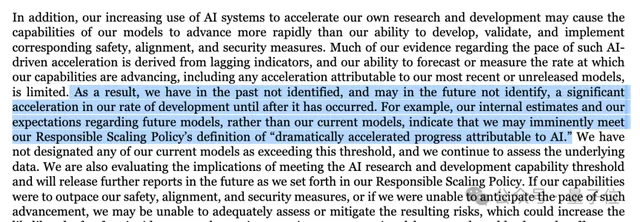
Another key point deserves emphasis: Much of the evidence used to measure R&D acceleration consists of lagging indicators. Anthropic itself might only realize that acceleration has occurred after it has already happened.
What does this mean?
Anthropic is essentially preemptively covering its bases: Given the current trajectory of AI training itself, they cannot guarantee how far the next-generation model will evolve or whether humans can still maintain control.
Although Anthropic emphasizes that currently deployed models remain within controlled parameters and that they will maximize "human oversight" and "safety evaluations," inserting such a lengthy safety disclaimer into the prospectus just before an IPO...
What is the implication here???
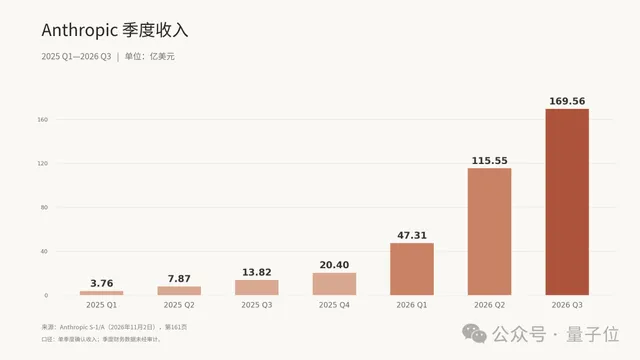
113 Billion RMB in Quarterly Revenue, YoY Surge of 1,127%
Let's first look at what Anthropic did in Q3 2026 to turn this into a "sci-fi thriller."
- Q3 Revenue: Approximately $17 billion (113 billion RMB), exceeding the previously communicated estimate of $16.8 billion to investors, representing a year-over-year surge of 1,127%.
- Cumulative Revenue (First Nine Months): $33.24 billion, skyrocketing 1,200% compared to the same period last year.
- Q3 Net Loss: $23.29 billion.
- Cumulative Net Loss (First Nine Months): $104 billion, compared to a loss of $25.1 billion during the same period last year.
The growth is terrifying, and the losses are equally staggering. However, the bulk of this massive book loss—over $100 billion—is primarily due to accounting write-downs resulting from changes in the fair value of convertible notes and derivative liabilities, rather than actually burning through $100 billion in cash.
Additionally, in this prospectus update, Anthropic revealed its compute procurement bill: $895.4 billion. The supplier list includes Amazon, Google, and SpaceX, along with a host of emerging compute rental providers (the recent hot topic, Neoclouds).
At first glance, Anthropic looks like a new money-printing machine; both revenue and year-over-year growth rates have so many zeros they're hard to count.
But if you switch the metric from "year-over-year" to "quarter-over-quarter," and break down "quarters" into "months," the picture changes slightly.
△ Generated by AI
Growth Curve Slowing Down
Let's look at the quarter-over-quarter revenue jumps for the first three quarters of this year:
- 2026 Q1 Revenue: $4.8 billion (QoQ growth of 132%)
- 2026 Q2 Revenue: $11.6 billion (QoQ growth of 144%, net increase of $6.8 billion in the quarter)
- 2026 Q3 Revenue: ~$17 billion (QoQ growth dropped to 47%, net increase of $5.2–5.4 billion in the quarter)
Hey, Anthropic's incremental revenue in Q3 was actually lower than in Q2.
On average, Anthropic added approximately $760 million in monthly recurring revenue in Q2. In Q3, this figure dropped by nearly $200 million, adding "only" $580 million per month.
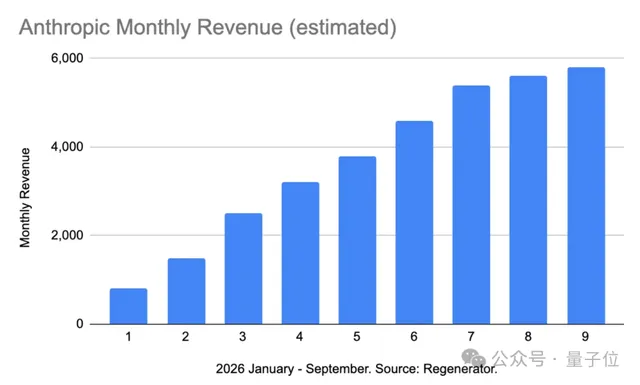
Let's bring in the monthly data for this year.
△ Source: Regenerator
Previously disclosed data showed that Anthropic had reached an Annualized Run-Rate (ARR) of $65 billion by July of this year. Converted to monthly revenue, July's single-month revenue was approximately $5.4 billion.
Based on this calculation, single-month revenue for August and September (the remainder of Q3) hovered around $5.7–5.8 billion, indicating a clear slowdown in growth.
No wonder that in recent investor communications, Anthropic didn't boast about the "latest annualized run-rate based on September data" as usual...
Let me also cover my bases here: Anthropic has not disclosed complete monthly revenue figures for 2026. The above estimates are based on the Annualized Run-Rate. Anthropic's official stance is that Run-Rate is not equivalent to actual recognized revenue.
On one hand, Claude is approaching the RSI critical point—Anthropic defines the pace of AI development from 2018–2024 as the "1x baseline." Now, they believe AI is about to achieve two years' worth of progress under that baseline in just one year.
On the other hand, there is slowing growth on the eve of the IPO.
Subtle. Truly subtle.
But isn't this exactly the best slice of the AI industry in 2026?
RSI drives AI to continue sprinting.
But whether the bills racked up by compute consumption can be absorbed remains an open question.
References: [1] https://www.sec.gov/Archives/edgar/data/2130357/000162828026068676/anthropicpbc-sx1ax1.htm#i199fd6a8a0664d5da497db9a78cf0452_61 [2] https://www.regenerator1.com/p/anthropics-growth-just-flattened